Retirement Annuities: The Importance of Beneficiary Nominations

Ruvan J Grobler • July 30, 2025

Your estate plan evolves as you get older and regular revision of beneficiary nominations on appropriate investments structures becomes a key planning tool. A holistic financial plan is the roadmap to executing these essential estate planning decisions. Let’s explore the importance of beneficiary nominations on your retirement annuity, pension-, provident or preservation funds.


Estate Planning:

  • Availability of funds: If the beneficiary nomination is valid, the death benefit will flow directly from the insurer to the beneficiary. This process can be much quicker than the process of winding up the estate. The death benefit can be paid to beneficiaries before other distributions from the estate is made.
  • Estate related fees: By nominating valid beneficiaries, there is no capital inclusion in the deceased’s estate for estate duty and executor fees. This makes it an effective planning tool in reducing the size of the estate and related fees.


Estate duty (SARS): 20% of the dutiable estate after R3.5mil and 25% after R30mil.

Executor’s fees: Maximum of 4.025% (Including VAT) of the deceased estate.


Very Important note:

Section 37C of the Pension Funds Act regulates the payment of death benefits. The act aims to identify dependants of the deceased and ensure that death benefit payments are made to them. The trustees appointed by the fund must identify these dependants irrespective of who was nominated by the deceased. The trustees have a duty to conduct a thorough investigation to ensure equitable distribution of death benefits and rely on the financial advisor to provide relevant facts.


What if no beneficiaries are nominated?

The above process will still follow but it could then be possible that a determination is made to pay the death benefit to the deceased’s estate. The capital will then form part of the estate for purposes of estate duty and executor’s fees. This may also be an intentional decision in order to provide cashflow in the estate for estate related costs or debt. There are however better options in planning for estate cashflow needs.


The above is not financial advice and serves only as factual information. Make sure these nominations align with your long-term financial goals and estate planning by consulting with your financial advisor.


Ruvan J Grobler RFP™ (PGDip Financial Planning)

By Bovest • October 7, 2026
When most people start thinking about their financial future, they go straight to the products. Which index fund is performing best right now? Should I put money into a tax-free savings account or property? What about offshore tech stocks? Those questions feel natural. But they won’t necessarily get you where you want to go. This article explains why the financial products you choose matter far less than the plan they serve. Learn how to craft a clear, holistic financial plan — not just a well-diversified portfolio — and discover what really determines whether you build lasting wealth. The importance of a holistic financial plan Selecting quality investments matters. That said: choosing products without a broader blueprint is like buying building materials before you have drafted the architectural blueprint. Because in the end, it is not simply a matter of creating wealth for the short run, it is about creating wealth for life. At Bovest, our foundation rests on a simple principle: an investment portfolio is merely the engine, but a holistic financial plan is the GPS that directs you on your route. What are the 5 components of a financial plan A holistic financial plan does not start with market performance or product features. It begins with context. A comprehensive plan connects five distinct areas of your life into one cohesive strategy:
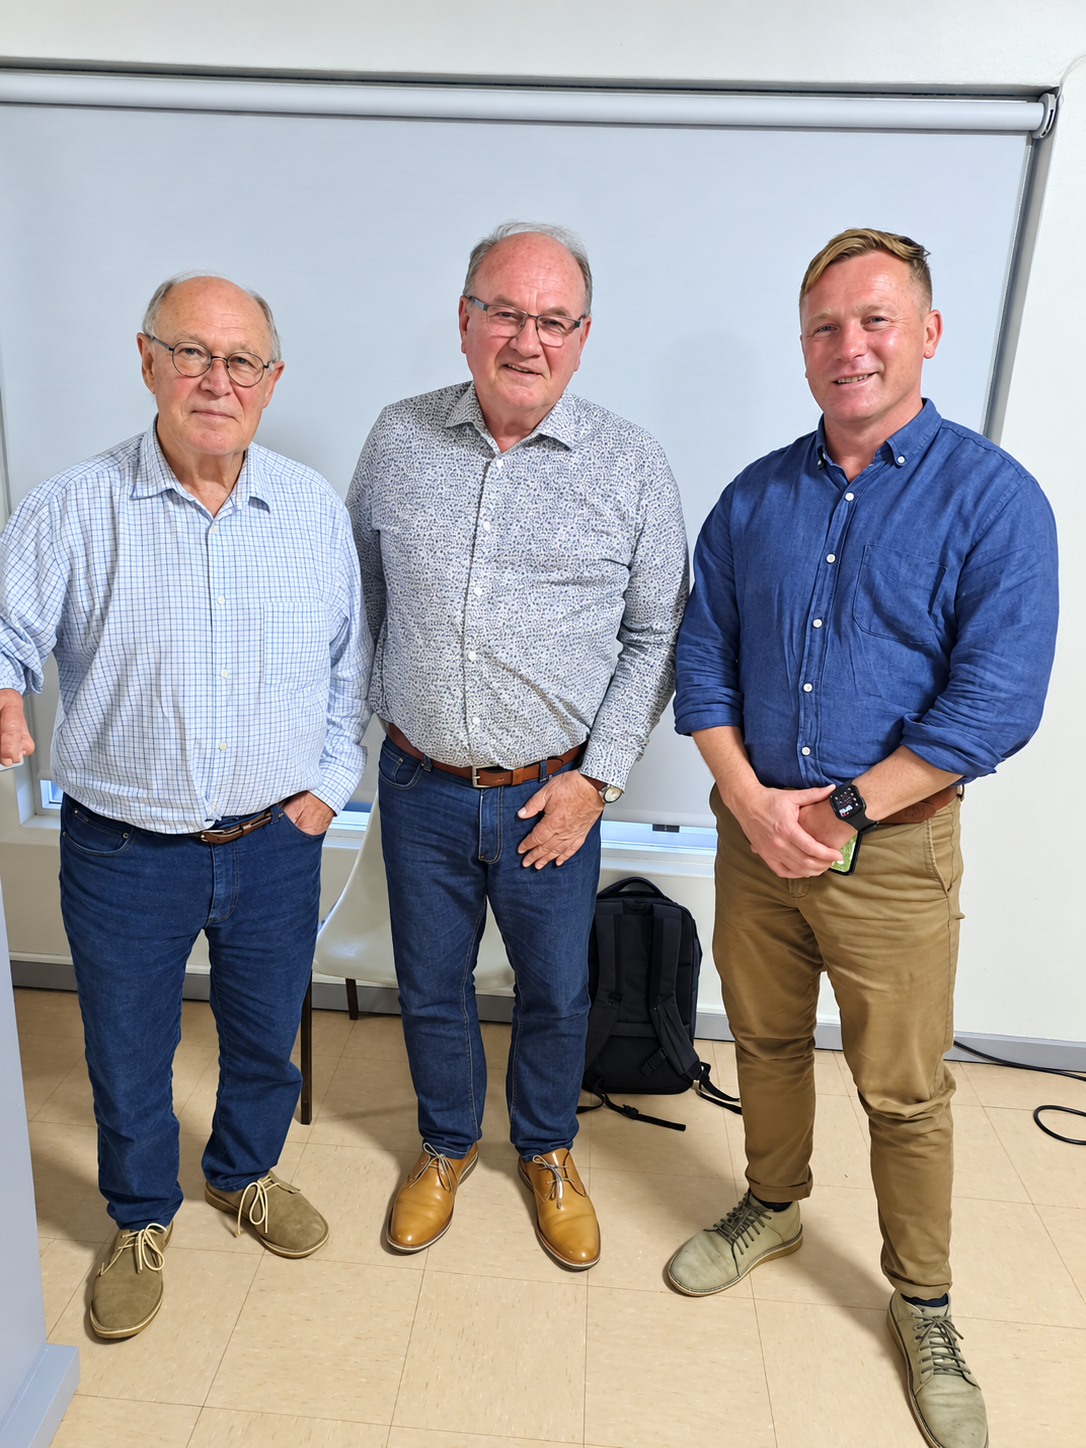
By Agulhas Besprekingsforum: Dr. Riaan Botha • October 1, 2026
Die gesprek het plaasgevind in Struisbaai se rolbal klubhuis en is bygewoon deur 35 persone. Die aanbieding wat ek gedoen het, het die persoonlike uitdagings van ’n welvaartskepper beskryf. Punte wat uitgelig is: Wat is jou passie? Kies ’n strategie om jou passie uit te leef. Kennis is die sleutel tot suksesvolle welvaartskepping. Leer goeie geld gewoontes aan. Positiewe uitkyk op die lewe - Beheer wat binne jou vermoë is. Bou ’n netwerk van goeie mense wat jy vertrou. Bou jou persoonlike handelsnaam. Welvaartskepping is ’n lang reis. Geen kitsrykdom nie. Bovest sal jou help met finansiële advies: Om persoonlike finansiële doelwitte te stel. Om ‘n monitor program op te stel vir beplande finansiële doelwitte. Daar het ’n goeie gesprek na die aanbieding gevolg. Die huidige werkloosheid situasie in SA is bespreek en dat veral jong mense hul eie besighede moet begin om persoonlike welvaart te skep. Aangesien die ’n ouer gehoor was in welvaart bewaring ook bespreek. Die voorsitter, Danie Schutte, het ten slotte sy dank uitgespreek dat daar ’n positiewe situasie vir welvaartskepping in SA uitgebeeld is. Dit is veral vir jong mense bemoedigend om nie oorsee te gaan werk soek nie maar hier plaaslik ’n inkomste te skep.